Payday Cash Advance TriceLoans

Screenshots
Details
- Rating
- 199.00 reviews
- Version
- 1.1.6
- Developer
- Trice Loans
Analysis by Norviv
When an unexpected bill lands between paydays, speed can matter more than a polished budgeting dashboard. That is the space where Payday Cash Advance TriceLoans tries to help: it is a finance app from Trice Loans built around requesting a short-term cash advance through a phone. After reviewing the app’s purpose and presentation, my clear impression is that it is most useful as an emergency option to investigate carefully, not as a routine way to stretch every paycheck.
The central trade-off is simple: the app makes access feel more direct, but convenience should never replace reading the full repayment terms. A quick application can be appealing when a utility payment, transport cost, or urgent household expense cannot wait. At the same time, a cash advance is still borrowing, and the decision only makes sense if the repayment fits comfortably into the next part of your budget.
What the app is really designed to do
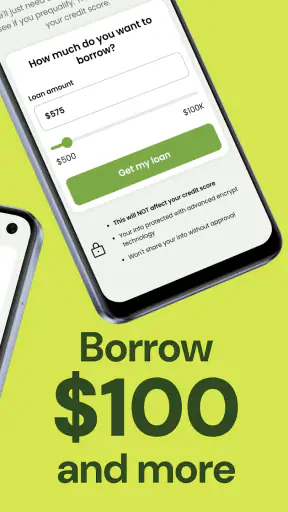
TriceLoans sits in the finance category rather than trying to be a general banking replacement. Its focus is payday-style borrowing and instant cash-advance requests, with an emphasis on a fast process and no traditional credit check. That positioning will immediately appeal to people who may have difficulty qualifying through conventional lenders, but it also means the app should be approached with more caution than a normal expense-tracking tool.
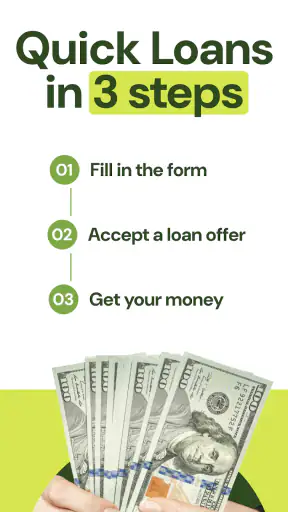
I found the concept easy to understand. You are not opening an investment account, setting up a full banking relationship, or learning a complicated financial platform. The intended journey is much narrower: consider an advance, review the offer and its conditions, then decide whether continuing is sensible for your situation. That narrow purpose is one of the app’s strengths because it avoids distracting features that do not help someone facing a time-sensitive expense.
The developer is listed as Trice Loans, and the app is free to install. It is rated for Everyone, which makes the presentation broadly accessible, although the financial decision itself is not suitable for every adult or every household. The current release is version 1.1.6, and it runs on Android 7.0 or later, so people using older devices may need to check compatibility before planning around it.
Its public reception is encouraging at first glance. The app holds a 4.7 average from around 7,200 ratings, with roughly 200 written reviews, and it has passed 50,000 installs. Those figures suggest that many people have been willing to try it, but they should not be mistaken for a promise that every applicant receives the same result. A finance app can be convenient while still producing an offer that is too expensive or unsuitable for a particular budget.
The first thing I would check before applying
I would begin by treating the opening screen as a screening tool rather than a guarantee. The phrase “no credit check” sounds reassuring, especially for someone worried about a damaged credit history, but it does not mean the advance is free, automatic, or without eligibility conditions. I would move through the process only far enough to understand what information is requested and what repayment obligation appears before accepting anything.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This is also where I would slow down over any optional-looking charge. The app includes in-app purchases ranging from $1.99 to $4.99 per item, so I would not assume that installing the app tells the whole cost story. Before proceeding, I would identify whether a displayed amount relates to the borrowing process, an optional service, or another app transaction, and I would make sure the final total is clear. If the cost cannot be understood in one sitting, I would stop rather than rely on the urgency of the moment.
That habit is especially important with short-term advances. A small amount can feel manageable when viewed only as money arriving today. The more useful calculation is the complete amount leaving later, alongside rent, food, transportation, subscriptions, and existing repayments. I would write those numbers down before accepting an offer, because an advance that solves one problem but creates a second shortfall is not a successful solution.
Where the focused design works well
The strongest part of TriceLoans is its focused purpose. Someone searching for an emergency advance does not have to sort through investment charts, credit-building lessons, or a large collection of unrelated tools. The app’s identity is immediately clear, and that can reduce decision fatigue when the user is already stressed.
I can imagine a realistic use case. Suppose a commuter’s car repair bill arrives just before payday and missing work would cost more than the repair itself. The person could use the app to explore whether an advance is available, compare the repayment obligation with the next paycheck, and decide whether the short-term cost is justified. In that situation, the app is useful as a fast way to investigate a possible bridge. It is not automatically the best answer, but it may be more practical than waiting for a lengthy conventional application.
Another strength is that the app’s purpose matches a specific financial moment. If you already know the exact amount needed and the exact date when repayment can be made, a focused cash-advance tool is easier to evaluate than a broad personal-loan marketplace. The narrower the need, the more helpful that simplicity becomes.
My practical tip is to use it only after creating a repayment checkpoint. Before submitting an application, I would note the expected payday, reserve money for essential bills, and decide the maximum repayment I can handle without borrowing again. If the advance would require another advance to cover ordinary expenses, that is a strong sign to consider a different solution.
What “fast” does not solve
The app’s biggest weakness is not necessarily its interface; it is the financial pressure built into the product category. Speed is valuable, but it can encourage a rushed decision. A person who is already anxious may focus on receiving money and overlook the total repayment amount, timing, or any associated charge. The app therefore demands more self-discipline than a typical finance application.
I also would not confuse an application that avoids a traditional credit check with guaranteed approval. The wording may make the process sound broadly available, yet an applicant still needs to review the actual result presented to them. If the amount offered is smaller than expected, the repayment date is awkward, or the cost makes the advance unreasonable, declining is the better outcome.
There is another important limitation for anyone seeking long-term financial improvement. TriceLoans is aimed at solving an immediate cash gap; it is not a substitute for building an emergency fund, negotiating a bill, increasing income, or repairing credit over time. Using it repeatedly can make the next payday feel permanently pre-spent. I would regard repeated use as a warning about the underlying budget rather than as evidence that the app is meeting its purpose well.
Because the app is free to download, it is easy to begin without feeling that a decision has already been made. That is helpful, but it can also lower the psychological barrier to borrowing. I would keep the app in the “compare and inspect” category until every cost and repayment detail is understood. The free installation should not be treated as free access to money.
How I would use it responsibly
My preferred workflow would take a few deliberate steps. First, I would define the emergency in one sentence and calculate the smallest amount that actually solves it. Borrowing more than necessary increases the repayment burden without improving the outcome. Second, I would check whether the bill provider offers a payment arrangement or whether a trusted person, employer option, or conventional bank product is less expensive.
Third, I would review the offer inside the app with the same attention I would give a paper contract. I would look for the amount received, the total amount repaid, the due date, and any separate transaction or service charge. Fourth, I would compare that obligation with the money already committed to essentials. Only after those checks would I decide whether continuing is reasonable.
A useful non-obvious safeguard is to avoid applying while multitasking. If you are standing in a checkout line, caring for a child, or dealing with a late-night emergency, it is easy to accept a figure without absorbing its consequences. I would wait until I could read the terms calmly and save a record of the offer for my own budgeting. That is not a criticism of one screen or one button; it is a necessary response to the speed of this type of borrowing.
I would also keep the app separate from everyday spending decisions. Opening it whenever a discretionary purchase feels difficult could turn an emergency tool into an extension of disposable income. The healthiest boundary is to reserve it for a defined, unavoidable expense and to remove the option from consideration once the need has passed.
Who will appreciate it, and who should skip it
TriceLoans is best suited to an adult who has a specific short-term need, understands the repayment schedule, and has a realistic plan for covering the obligation. It may also be worth examining for someone who expects conventional credit checks to be a barrier and wants to see whether an alternative application route is available.
I would recommend skipping it if your income is already committed before the next payday, if you are unsure when repayment will be possible, or if you are considering borrowing for recurring groceries, rent, or utilities. Those situations point to a larger cash-flow problem that a single advance is unlikely to fix. A nonprofit financial counselor, a bill-negotiation service, a credit union, or a direct payment arrangement may be a better direction, depending on the circumstances.
It is also not the right choice for someone who wants a complete personal-finance system. If your priority is tracking spending, setting savings goals, monitoring accounts, or improving credit habits, a budgeting or credit-building app will offer a more appropriate focus. Traditional lenders may be preferable when they provide a lower overall cost and a repayment period that does not collide with the next paycheck.
For parents or shared households, I would add one practical caution: discuss the repayment plan with anyone who depends on the same income. A cash advance can look like an individual fix on a phone screen while affecting food, transportation, or household bills later. The app cannot make that family-level decision for you, so the responsibility remains with the person applying.
My final assessment of the experience
After looking at what Payday Cash Advance TriceLoans is built to do, I see a straightforward emergency-borrowing tool with a clear audience. Its strongest qualities are its focused purpose, accessible entry point, and appeal to people who may not want a traditional credit-check process. The 4.7 average and growing install base show that the concept has attracted substantial interest, but neither should replace personal due diligence.
The meaningful drawback is the same feature that makes the app attractive: speed. Fast access can be valuable during a genuine emergency, yet it can also make expensive borrowing feel too easy. The presence of per-item in-app purchases reinforces why I would inspect every amount before accepting an offer rather than judging the service by its download price.
My recommendation is conditional: use it as a comparison point for one clearly defined emergency, never as a routine payday supplement. I would install it only when I had already calculated the smallest amount needed and identified how repayment would fit alongside essential bills. If the terms are clear and manageable, it may provide a practical route to investigate. If the cost or timing strains the budget, I would close it and pursue a payment arrangement, credit-union option, employer resource, or other lower-risk alternative instead.
In short, TriceLoans can be useful when the problem is temporary, the repayment plan is certain, and the user reads beyond the promise of convenience. It is not a replacement for savings or sustainable budgeting, and it should not be treated as one. For a careful borrower facing a genuine short gap, it is worth examining; for someone already relying on advances to get through ordinary weeks, choosing a different financial solution is the wiser move.
Frequently Asked Questions
01What is Payday Cash Advance TriceLoans?
Payday Cash Advance TriceLoans is presented as a short-term borrowing service designed to help users request funds before their next payday. The application may collect personal, employment, banking, and contact information during the application process. It is important to understand that TriceLoans may act as a connection service rather than a direct lender, so approval, loan terms, and funding depend on participating providers.
02Who can apply for a loan through Payday Cash Advance TriceLoans?
Eligibility requirements can vary depending on the lender matched through the service, but applicants generally need to meet age, residency, income, employment, and active bank-account requirements. Approval is not guaranteed, even when an application is submitted successfully. Before applying, review the service’s privacy policy, lender disclosures, repayment schedule, annual percentage rate, fees, and any additional conditions that may affect the total cost.
03How much does a Payday Cash Advance TriceLoans loan cost?
The total cost depends on the lender, loan amount, repayment period, interest rate, and applicable fees. Short-term loans can be considerably more expensive than traditional personal loans, particularly when expressed as an annual percentage rate. Do not focus only on the amount deposited into your account; carefully compare the finance charge, due date, late-payment consequences, and total amount you will be required to repay.
04How quickly can I receive money through TriceLoans?
The application process may be completed quickly, but submitting an application does not guarantee instant approval or immediate funding. A lender may need to verify your identity, income, and banking details before making a decision. If approved, the time for funds to arrive can depend on the lender and your bank, and electronic transfers may not appear until the next business day or later.
05Is Payday Cash Advance TriceLoans safe to use?
Use caution and verify all information before sharing sensitive data or accepting an offer. Check that the application is obtained from an official source, read its permissions and privacy policy, and confirm the identity of any lender contacting you. Never pay an upfront fee to receive a promised loan, and avoid providers requesting gift cards, cryptocurrency, or unusual payment methods. Only accept terms you can repay on time.


